Loading
13 rows in this plan print blank.Fill them in
Thesis
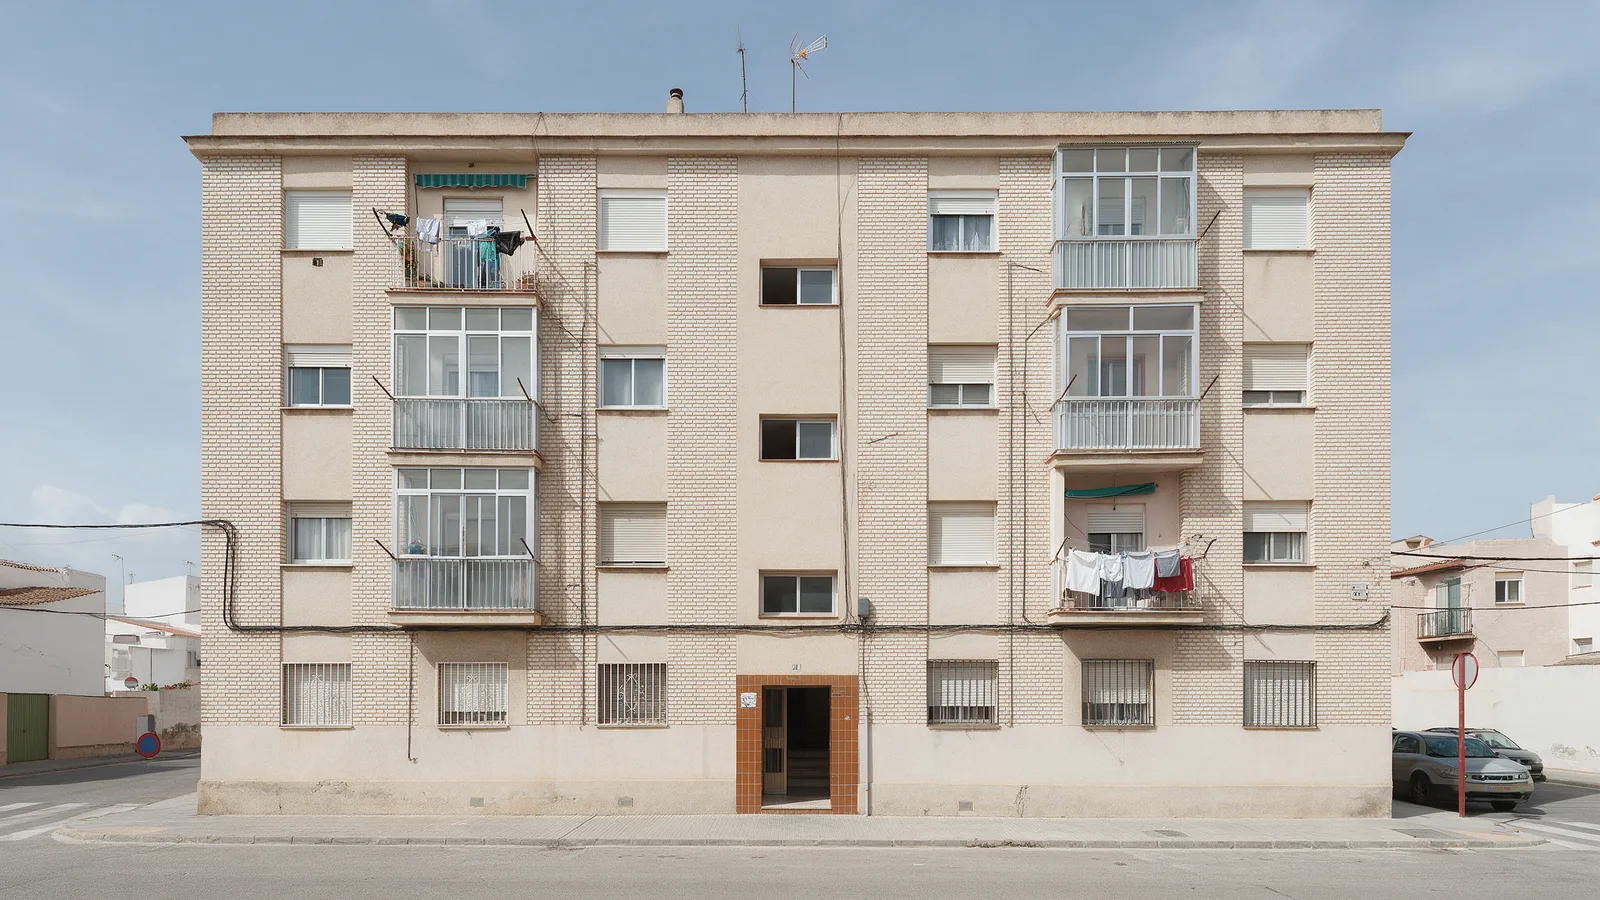
A fourteen-room hostal in Benimaclet, four minutes from the tram and inside the student ring. Why it is available: the owner is a builder who took the building in part-payment for work and does not want to run it (The seller needs out). What we do: refurbish the fourteen rooms and the ground-floor breakfast room, run them by the night for the university's visitors and the tram's commuters, and hold. What has to be true: · 100-128 EUR a night at the house 82 % — the rate the two hostales on the tram line already take. · The technical survey comes back without structural work. · The hostal licence transfers with the building.
The ask
LP equity sought
737.660 €
at 50 % LTV
Target LP IRR
14,5 %
projected, not promised
LP equity multiple
3,05×
over 10 years
First capital call
Not modelled
the plan carries no dates
At a glance
Asking price
1.750.000 €
Total project cost
1.798.776 €
Cost per unit
128.484 €
Units
14
Stabilised NOI
157.263 €
NOI margin
37 %
Yield on cost
8,74 %
Leveraged yield (at 50 % debt)
17,49 %
LP IRR
14,5 %
Hold period
10 years
Key dates
Reserva
—
DD deadline
—
Arras
—
Escritura
—
Works complete
—
Opening
—
Assumptions template MASTER v2. Figures are projections rather than forecasts or guarantees, and follow from the assumptions set out in this document. Prepared for discussion among Marisol and its investors; not an offer or a solicitation.
Property
FormatHostal
Deal type—
Units14
Gross m²1.030
Net m²874
AreaBenimaclet · Valencia
Regulatory
Licence type—
Licence status—
Expediente—
Unit mix and pricing
Nightly rates and cleaning fees include IVA; the model deducts it.
| Line | Type | Net m² | ADR | Cleaning | Monthly rent |
|---|---|---|---|---|---|
| Room · hostal | STR | 22 | 100 € | — | — |
| Room · terrace | STR | 30 | 128 € | — | — |
From price to total project cost
What it costs to own the building, ready to trade.
Purchase price1.400.000 €
ITP (transfer tax)84.000 €
AJD (stamp duty)10.500 €
Broker commission42.000 €
Due diligence7.000 €
Notary, registry, SPV, tax advisory8.700 €
Total acquisition costs152.200 €
Renovation and fit-out61.000 €
FF&E, IT and locks109.600 €
Permits, licensing, architect40.000 €
Cost base1.762.800 €
GP setup fee35.976 €
Total project cost1.798.776 €
Per unit128.484 €
The GP's structuring fee (1 %) sits in every cost base; its financing fee (1 %) only where the deal is financed, so an all-equity structure carries the first and not the second.
Exit
Capitalised at the exit-year NOI.
Exit-year NOI (year 10)180.646 €
Exit cap rate7,00 %
Gross exit price2.580.655 €
Selling costs-51.613 €
Net exit proceeds2.529.042 €
The ramp
Total operating revenue, GOP and NOI. The dashed line is occupancy, on its own scale.
Profit and loss, 10 years
Figures in € thousands; margins on total operating revenue. Stabilised from operating year 3. USALI order: revenue, departmental and undistributed expenses, GOP before any management fee, the fees, the owner's charges, EBITDA, the reserve, NOI.
| Line | Y1 | Y2 | Y3 | Y4 | Y5 | Y6 | Y7 | Y8 | Y9 | Y10 | Total |
|---|---|---|---|---|---|---|---|---|---|---|---|
| Occupancy | 76 % | 79 % | 82 % | 82 % | 82 % | 82 % | 82 % | 82 % | 82 % | 82 % | 82 % |
| Blended ADR incl. IVA | 103 | 108 | 110 | 112 | 115 | 117 | 119 | 122 | 124 | 127 | — |
| Blended ADR ex-IVA | 93 | 98 | 100 | 102 | 104 | 106 | 108 | 111 | 113 | 115 | — |
| Accommodation | 362k | 396k | 420k | 428k | 437k | 445k | 454k | 463k | 473k | 482k | 4360k |
| Total operating revenue | 362k | 396k | 420k | 428k | 437k | 445k | 454k | 463k | 473k | 482k | 4360k |
| Platform commission | -62k | -67k | -71k | -73k | -74k | -76k | -77k | -79k | -80k | -82k | -741k |
| Cleaning | -42k | -44k | -47k | -48k | -49k | -50k | -51k | -52k | -53k | -54k | -491k |
| Linen | -8k | -8k | -9k | -9k | -9k | -9k | -9k | -10k | -10k | -10k | -91k |
| Amenities | -5k | -5k | -5k | -5k | -5k | -6k | -6k | -6k | -6k | -6k | -55k |
| Building manager | -15k | -15k | -16k | -16k | -16k | -17k | -17k | -17k | -18k | -18k | -164k |
| Extended appliance warranty | -1k | -1k | -1k | -1k | -1k | -1k | -1k | -1k | -1k | -1k | -7k |
| Departmental expenses | -132k | -141k | -149k | -152k | -155k | -158k | -161k | -164k | -167k | -171k | -1549k |
| Departmental profit | 231k | 255k | 271k | 276k | 282k | 288k | 293k | 299k | 305k | 311k | 2812k |
| Departmental profit margin | 64 % | 64 % | 65 % | 65 % | 65 % | 65 % | 65 % | 65 % | 65 % | 65 % | 65 % |
| Admin / accounting | -2k | -2k | -2k | -3k | -3k | -3k | -3k | -3k | -3k | -3k | -26k |
| Administrative & general | -2k | -2k | -2k | -3k | -3k | -3k | -3k | -3k | -3k | -3k | -26k |
| Full technical survey | -3k | 0k | 0k | 0k | 0k | 0k | 0k | 0k | 0k | 0k | -3k |
| Information & telecom | -3k | 0k | 0k | 0k | 0k | 0k | 0k | 0k | 0k | 0k | -3k |
| Maintenance | -4k | -5k | -5k | -5k | -5k | -5k | -5k | -6k | -6k | -6k | -52k |
| Property operation & maintenance | -4k | -5k | -5k | -5k | -5k | -5k | -5k | -6k | -6k | -6k | -52k |
| Utilities + community | -23k | -23k | -24k | -24k | -25k | -25k | -26k | -26k | -27k | -28k | -252k |
| Utilities | -23k | -23k | -24k | -24k | -25k | -25k | -26k | -26k | -27k | -28k | -252k |
| Undistributed expenses | -33k | -31k | -31k | -32k | -33k | -33k | -34k | -35k | -35k | -36k | -333k |
| GOP | 198k | 225k | 239k | 244k | 249k | 254k | 259k | 264k | 270k | 275k | 2478k |
| GOP margin | 55 % | 57 % | 57 % | 57 % | 57 % | 57 % | 57 % | 57 % | 57 % | 57 % | 57 % |
| Management fee — 15,5 % of total operating revenue | -56k | -61k | -65k | -66k | -68k | -69k | -70k | -72k | -73k | -75k | -676k |
| Management fees | -56k | -61k | -65k | -66k | -68k | -69k | -70k | -72k | -73k | -75k | -676k |
| GOP the fees are measured on | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | — |
| Income before non-operating | 142k | 163k | 174k | 178k | 181k | 185k | 189k | 193k | 196k | 200k | 1802k |
| Property tax (IBI) | -4k | -4k | -4k | -4k | -4k | -4k | -4k | -4k | -5k | -5k | -43k |
| Insurance | -3k | -3k | -3k | -3k | -3k | -3k | -3k | -3k | -3k | -3k | -28k |
| Non-operating | -6k | -7k | -7k | -7k | -7k | -7k | -7k | -7k | -8k | -8k | -70k |
| EBITDA | 135k | 157k | 168k | 171k | 175k | 178k | 182k | 185k | 189k | 193k | 1732k |
| FF&E reserve | -9k | -10k | -10k | -11k | -11k | -11k | -11k | -12k | -12k | -12k | -109k |
| NOI | 126k | 147k | 157k | 160k | 164k | 167k | 170k | 174k | 177k | 181k | 1623k |
| NOI margin | 35 % | 37 % | 37 % | 37 % | 37 % | 37 % | 37 % | 37 % | 37 % | 37 % | 37 % |
Financing scenarios
The highlighted row is the basis Marisol quotes.
| Scenario | LTV | Senior debt | All-in rate | Debt service | DSCR | Total equity | LP equity | LP IRR | LP × |
|---|---|---|---|---|---|---|---|---|---|
| No debt | 0 % | 0 € | — | — | — | 1.780.606 € | 1.424.485 € | 10,97 % | 2,26× |
| 50% LTV | 50 % | 899.388 € | 2,75 % | 73.241 € | 2,15 | 922.075 € | 737.660 € | 14,50 % | 3,05× |
| 60% LTV | 60 % | 1.079.265 € | 2,75 % | 87.890 € | 1,79 | 745.885 € | 596.708 € | 15,87 % | 3,42× |
From NOI to cash
On the 50% LTV basis. What the lender is owed before anything reaches equity. Coverage is year by year, so it opens below the stabilised figure above and climbs as the building fills. Figures in € thousands.
| Line | Y1 | Y2 | Y3 | Y4 | Y5 | Y6 | Y7 | Y8 | Y9 | Y10 | Total |
|---|---|---|---|---|---|---|---|---|---|---|---|
| NOI | 126k | 147k | 157k | 160k | 164k | 167k | 170k | 174k | 177k | 181k | 1623k |
| Loan interest | -24k | -23k | -21k | -20k | -18k | -17k | -15k | -14k | -12k | -10k | -175k |
| Principal repaid | -49k | -50k | -52k | -53k | -55k | -56k | -58k | -60k | -61k | -63k | -558k |
| Cash after debt service | 53k | 74k | 84k | 87k | 90k | 94k | 97k | 100k | 104k | 107k | 891k |
| DSCR | 1,73 | 2,00 | 2,15 | 2,19 | 2,23 | 2,28 | 2,32 | 2,37 | 2,42 | 2,47 | — |
| Cumulative cash | 53k | 127k | 211k | 298k | 388k | 482k | 579k | 679k | 783k | 891k | — |
Waterfall, 50% LTV
At 50 % LTV. The distributable column is the cash line from the page before. Figures in € thousands, except yield.
| Year | Distributable | Tier A | Tier B | Tier C | LP | GP | LP yield |
|---|---|---|---|---|---|---|---|
| Y1 | 53k | 53k | 0k | 0k | 43k | 11k | 5,8 % |
| Y2 | 74k | 74k | 0k | 0k | 59k | 15k | 8,0 % |
| Y3 | 84k | 84k | 0k | 0k | 67k | 17k | 9,1 % |
| Y4 | 87k | 87k | 0k | 0k | 70k | 17k | 9,5 % |
| Y5 | 90k | 90k | 0k | 0k | 72k | 18k | 9,8 % |
| Y6 | 94k | 94k | 0k | 0k | 75k | 19k | 10,2 % |
| Y7 | 97k | 97k | 0k | 0k | 78k | 19k | 10,5 % |
| Y8 | 100k | 100k | 0k | 0k | 80k | 20k | 10,9 % |
| Y9 | 104k | 104k | 0k | 0k | 83k | 21k | 11,3 % |
| Y10 | 107k | 107k | 0k | 0k | 86k | 21k | 11,6 % |
When the money comes back
Capital out, cash back, and the running position. The dashed line is where the LP is whole.
On exit
Loan balance repaid-341.780 €
Net proceeds after debt2.187.262 €
Tier A, pro rata to capital746.920 €
Tier B, to the hurdle728.034 €
Tier C, above the hurdle712.307 €
LP receives on exit1.534.545 €
GP receives on exit652.717 €
Over the hold
LP equity in737.660 €
LP from operations712.451 €
LP on exit1.534.545 €
LP total received2.246.996 €
LP multiple3,05×
LP IRR14,50 %
LP average yield on equity9,66 %
GP equity in184.415 €
GP total received830.830 €
GP multiple4,51×
Stabilised occupancy against ADR
LP IRR at the reporting basis, on the two levers that stay open after the price is agreed. The outlined cell is the base case.
| ADR | 76% | 79% | 82% | 85% | 88% |
|---|---|---|---|---|---|
| 97 € | 14,5 % | 14,5 % | 14,5 % | 14,5 % | 14,5 % |
| 103 € | 14,5 % | 14,5 % | 14,5 % | 14,5 % | 14,5 % |
| 108 € | 14,5 % | 14,5 % | 14,5 % | 14,5 % | 14,5 % |
| 113 € | 14,5 % | 14,5 % | 14,5 % | 14,5 % | 14,5 % |
| 119 € | 14,5 % | 14,5 % | 14,5 % | 14,5 % | 14,5 % |
Exit year against exit cap rate
LP IRR again. A shorter hold raises the rate and lowers the money: the equity multiple beside it falls as this table rises.
| Exit cap rate | Year 5-5 | Year 6-4 | Year 7-3 | Year 8-2 | Year 10 |
|---|---|---|---|---|---|
| 6.00% | 20,5 % | 18,9 % | 17,8 % | 17,0 % | 15,8 % |
| 6.50% | 18,7 % | 17,5 % | 16,7 % | 16,0 % | 15,1 % |
| 7.00% | 17,0 % | 16,2 % | 15,7 % | 15,2 % | 14,5 % |
| 7.50% | 15,5 % | 15,1 % | 14,7 % | 14,4 % | 14,0 % |
| 8.00% | 14,1 % | 14,0 % | 13,8 % | 13,7 % | 13,5 % |
Prepared 10 November 2026 from the current business plan against assumptions template MASTER v2. Every figure in this document is computed from the assumptions printed in the appendix; none is entered by hand.
Projections are not forecasts or guarantees. Returns depend on assumptions that will not all prove correct, and property investment carries the risk of loss including of capital. Prepared for discussion among Marisol and its investors; not an offer, a solicitation, or investment advice.
© 2026 Marisol. All rights reserved.
marks a value set for this deal. Everything else is inherited from the house template, so a change to firm policy carries through.
Revenue
Stabilised occupancy82 %
Year 1 occupancy ramp92,7 %
Year 2 occupancy ramp96,3 %
Year 1 ADR ramp95 %
ADR inflation2 %
Average length of stay2.5 nights
IVA rate10 %
Operating costs
Platform commission17 %
Management fee15,5 %
Community, per unit / month12 €
Maintenance1,2 %
IT, per unit / month40 €
Insurance, per unit / month15 €
Admin, monthly200 €
Utilities, per unit / month125 €
IBI, annual3.900 €
FF&E reserve2,5 %
Cost inflation2 %
Acquisition
Tax regimeITP / AJD
Broker commission3 %
Notary fee1.800 €
Registry fee900 €
Due diligence0,5 %
SPV setup3.500 €
Tax advisory2.500 €
GP setup fee2 %
Works and capex
Renovation levelUplift
Renovation, per unit0 €
Appliances, per unit2.000 €
Common areas24.000 €
Permits and licensing21.000 €
Architect and technical13.000 €
Interior design and procurement—
Contingency0 %
Exit
Exit cap rate7 %
Selling costs2 %
Waterfall terms
GP equity share20 %
Preferred return (LP IRR)8 %
Hurdle (LP IRR)12 %
LP split, pref to hurdle70 %
LP split, above the hurdle60 %